Fed continues to raise interest rates to solve inflationary pressure.
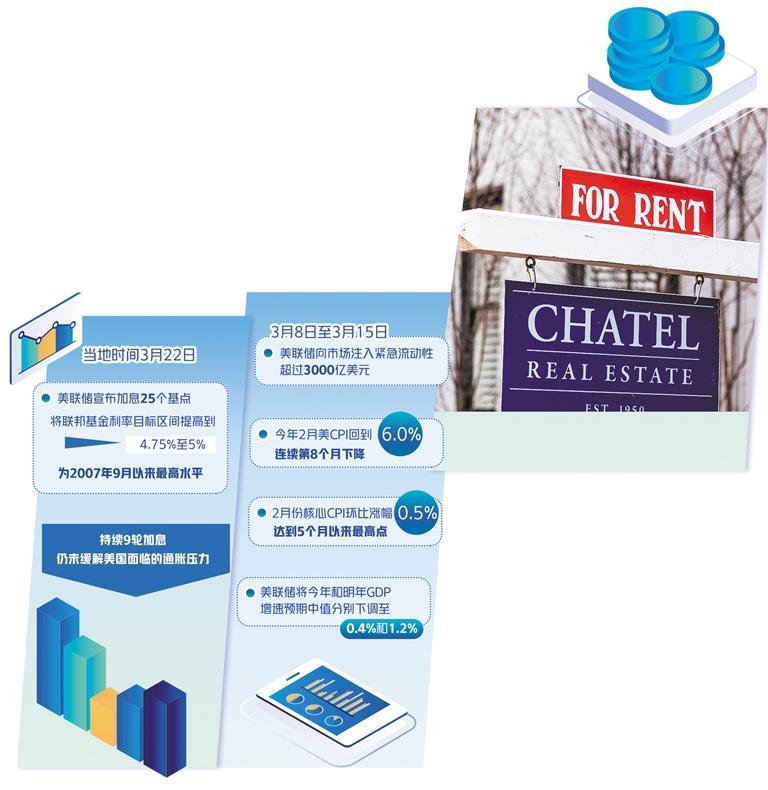
This is the information of the house for rent, which was shot in Washington, USA on March 14th. (Xinhua News Agency)
On March 22nd, local time, the Federal Reserve announced a 25 basis point interest rate hike, raising the federal funds rate to 4.75% to 5%, the highest level since September 2007. However, nine rounds of interest rate hikes have not eased the inflationary pressure facing the United States. From a global perspective, uncertainties that affect the instability of the world economy and push up inflation still exist. Disturbances on energy and food prices such as geopolitical conflicts, as well as sanctions and counter-sanctions imposed by the United States and Europe on Russia, will affect the stability of the global supply chain, thus further pushing up inflation. The economic prospects of the United States are still not optimistic, and financial risks cannot be ignored.
Between curbing the banking crisis and worrying about inflation, the Fed chose the latter. On March 22nd, local time, the Federal Reserve announced that it would raise interest rates by 25 basis points after the second monetary policy meeting this year, raising the target range of federal funds interest rate to 4.75% to 5%, the highest level since September 2007. Nine rounds of interest rate hikes have not eased the inflationary pressure facing the United States. On the same day, Federal Reserve Chairman Powell said that he would continue to assess the impact of the credit crunch, and it is still too early to change the policy direction because of the banking turmoil.
The focus of the Fed’s work is still on reducing inflation, but the tone of monetary policy tightening has eased a lot. First of all, the statement on interest rates was more moderate, deleting the wording "it is appropriate to continue raising interest rates" in the February meeting and replacing it with "some additional policy tightening may be appropriate". Secondly, the constraint of financial risks on monetary policy is becoming more and more obvious. Powell said that before the Silicon Valley Bank "thundered", the Federal Reserve was originally prepared to raise interest rates more sharply because of the good economic data at the beginning of the year, and the bankruptcy of the Silicon Valley Bank made this plan fall through. However, Powell insisted that the US banking system "remains stable as a whole" and tried to downplay the negative impact of interest rate hikes.
Before the meeting, because of the bankruptcy of Silicon Valley Bank, there was a lot of domestic demand for the Federal Reserve to stop raising interest rates or even cutting interest rates. All parties in the United States believe that it underestimated the potential impact of this round of banking turmoil. Us treasury secretary yellen said recently that the core problem of the closure of silicon valley bank is that the fed continues to raise interest rates, which leads to the continuous decline in the market price of financial assets such as bonds held by the bank, rather than the technology industry. Some people think that the Fed should stop raising interest rates and guide the economy by habitually and irreversibly raising or lowering interest rates, which will only make the economy suffer losses.
It is worth noting that although the Fed insists on the strategy of continuing to raise interest rates, it "secretly releases water" on the other side. In order to save the banking crisis, from March 8 to March 15, the Federal Reserve injected more than $300 billion in emergency liquidity into the market, half of which came from the funds lent by American banks from the discount window of the Federal Reserve, and the other half was the loan funds provided by the Federal Deposit Insurance Corporation (FDIC). The Fed has also launched a brand-new tool — — Bank term financing plan (BTFP). Some analysts believe that the effectiveness of this tool is almost equivalent to directly cutting interest rates, which will further solidify inflation expectations.
At present, although inflation in the United States has cooled down, it is still difficult to control. From the perspective of the United States, driven by the fall in energy prices, the year-on-year growth rate of the consumer price index (CPI) in February this year was the lowest since September 2021, returning to 6.0%, falling for the eighth consecutive month. However, inflation is still stubborn. At present, CPI is still at a high level, and the rate of decline is obviously weakened. In terms of core inflation, especially non-housing core inflation — — This part of inflation, supported by service and labor prices, is still sticky. In February, the core CPI rose by 0.5% month-on-month, exceeding market expectations and reaching the highest point in five months.
From a global perspective, uncertainties that affect the instability of the world economy and push up inflation still exist. Disturbances on energy and food prices such as geopolitical conflicts, as well as sanctions and counter-sanctions imposed by the United States and Europe on Russia, will affect the stability of the global supply chain, thus further pushing up inflation. In the eyes of the industry, not all problems can be solved by monetary tightening, such as inflation caused by supply shocks, which is essentially the result of imbalance between supply and demand in the real economy and needs to be solved by rebalancing supply and demand.
The economic outlook of the United States is still not optimistic. In the economic forecast in March, the Fed lowered the median GDP growth forecast for this year and next year to 0.4% and 1.2% respectively, and raised the median inflation forecast for this year and next year and the price index of core personal consumption expenditure (PCE) excluding food and energy to 3.6% and 2.6% respectively. It may be difficult for the United States to achieve a "soft landing" of inflation while avoiding economic recession. Historical data shows that under the pressure of high inflation, the Fed has to accept the rise in unemployment rate in exchange for effective control of price stability. Since 1950, the Federal Reserve has deflated 10 times, 8 of which have experienced economic recession, and the greater the deflation, the deeper the economic recession may be. In addition, the bitmap of the Federal Reserve’s interest rate hike path predicts that the median federal funds rate will be 5.1% at the end of 2023. This means that there is little room for the Fed to raise interest rates further, and it will soon face the turning point of the interest rate hike cycle.
The financial risks in the United States cannot be ignored. On the one hand, it is difficult to resolve the liquidity risk of the banking industry. Some calculations show that the actual value of American banking assets is $2 trillion lower than the book value considering the price fluctuation of "held-to-maturity" bonds. More seriously, a large number of deposits are not covered by American insurance companies. Once uninsured depositors run deposits, banks with insufficient liquidity are likely to be unable to cope, and their vulnerability will increase significantly. On the other hand, the credit crunch of small and medium-sized banks in the United States will impact the real economy. According to Goldman Sachs data, small and medium-sized banks with assets less than $250 billion bear about 50% of commercial and industrial loans in the United States, including 60% housing loans, 80% commercial real estate loans and 45% consumer loans.
After this regular meeting, Powell said that if the economic situation develops as predicted, the Fed will not cut interest rates this year. But if the economic situation changes, the policy direction will be adjusted accordingly. It can be seen that the Fed wants to wait and see for a while for the increase and the decrease and when to pause. Some analysts believe that the risk exposure of the US banking industry is precisely because the Fed failed to respond to the high inflation rate in time and raised interest rates too late and too fiercely. As the expected growth rate of the US economy continues to decline and the recession expectation continues to rise, there is not much time left for the Fed to make decisions.